

Jim: sell & get paid instantly

- 472.00 Reviews
- 4.4
- Downloads
- 100,000+
Our take on Jim: sell & get paid instantly from Appgk
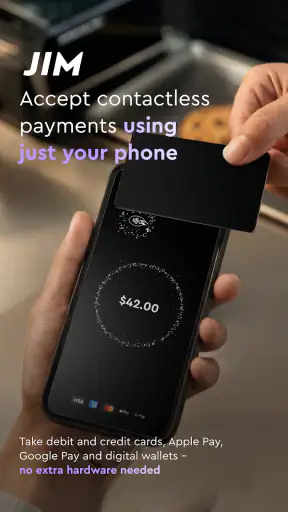
I tried Jim as a finance app built around a simple idea: use your phone as the point where a customer pays. That makes it more interesting than a conventional wallet, but also more dependent on how clearly the payment flow fits your everyday selling routine. Jim is developed by CloudWalk, costs nothing to install, and is aimed at people who want to accept card payments without carrying a separate card terminal.
My first impression was that Jim makes the most sense when payment collection is occasional, mobile, and personal. Think of a market stall, a home service, a small event, or a freelancer who does not want to send every customer to a separate checkout. The app belongs in the finance category, carries an Everyone age rating, and has already passed the early-experiment stage with more than one hundred thousand installs. Its average score sits at 4.4 from roughly two thousand ratings, which suggests that the basic idea is landing well with many users.
That said, I would not treat a phone card reader as an automatic replacement for every payment setup. The real question is not whether the app can make your phone part of a sale. It is whether that approach matches your volume, your customer habits, and your need for a broader business system. After using it with that question in mind, I found Jim most appealing as a focused payment tool rather than a complete retail platform.
How the everyday payment workflow feels
The natural starting point is a sale made away from a counter. I picture a local photographer finishing a small job, a repair worker collecting after a visit, or a seller meeting a customer at a community market. Instead of asking for a bank transfer or relying on cash, the seller can bring the payment moment into the same phone they already carry. That removes one piece of equipment from the routine and can make the interaction feel more direct.
Best Parts of Jim: sell & get paid instantly
Things to Keep in Mind About Jim: sell & get paid instantly
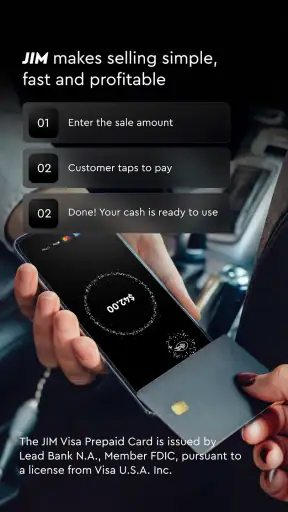
The useful habit is to prepare before the customer is standing in front of you. I would open Jim, check that the phone is ready, and make sure the amount is clear before beginning the transaction. This sounds obvious, but payment apps are least comfortable when the seller is searching through menus, switching between apps, or trying to remember the price while the buyer waits. A short pre-sale check makes the experience feel deliberate rather than improvised.
For a simple one-off sale, the appeal is obvious. You do not need to maintain a separate terminal in your bag, remember to charge another device, or hand the customer a payment machine that was designed for a much larger operation. The phone becomes the center of the interaction. I especially like that model for people whose work changes location throughout the day.
News and Features Related to Jim: sell & get paid instantly

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
There is also a social advantage. A customer may be more comfortable paying on a familiar-looking phone than entering details into an unfamiliar process, although the exact experience will depend on the payment method and the devices involved. I would still explain each step calmly and let the buyer see the amount before confirming. Speed is useful, but confidence matters more when money changes hands.
One practical workflow I would recommend is to separate the sale from the record-keeping. Jim can be the payment point, while a simple notebook, spreadsheet, or existing accounting routine tracks what was sold, to whom, and for which job. That distinction is important because a payment tool is not automatically an inventory manager or bookkeeping system. Keeping those responsibilities clear prevents the common mistake of assuming that a successful payment also creates a complete business record.
Don't want to read the full review?
Who benefits most from a phone-based reader
Jim feels particularly suitable for independent sellers who have a small catalog, straightforward prices, and no need for a large checkout screen. A tutor collecting after a lesson, a craft seller taking payment at a fair, or a technician finishing a call can all understand the attraction. In these cases, portability matters more than a deep register system.
It can also suit a business that already accepts transfers or cash but wants another option for customers who prefer cards. The app does not have to become the only payment channel. I see it as a useful addition when the seller wants to avoid losing a sale simply because the buyer does not carry cash or does not want to use a transfer.
Screenshots
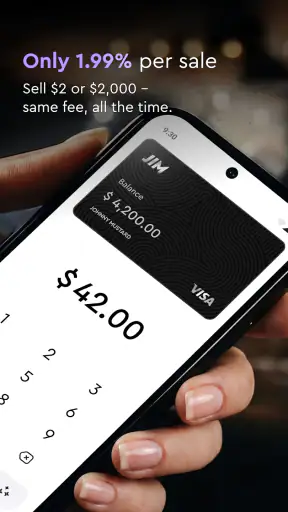
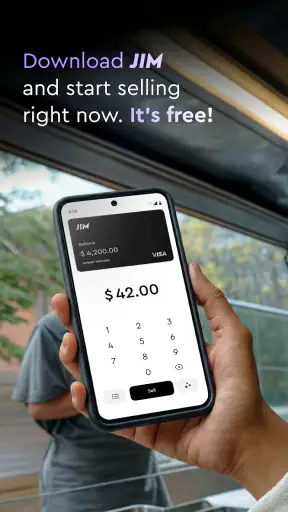
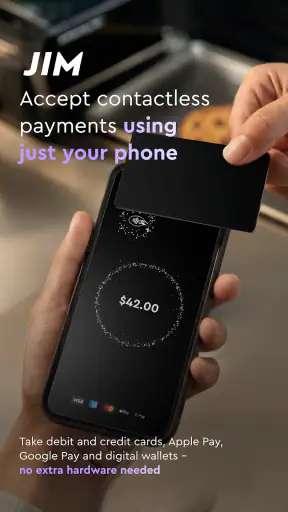
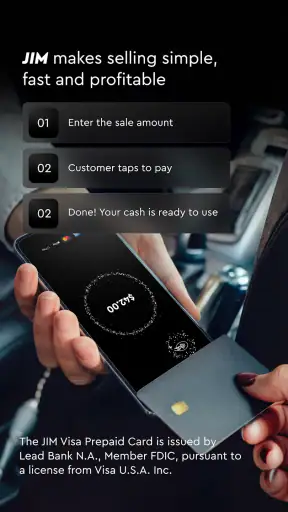
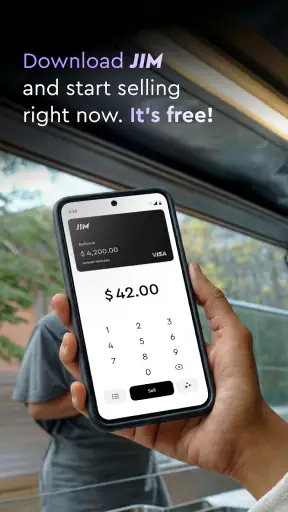
I would be more cautious for a busy store with several employees, many products, refunds, detailed stock control, and end-of-day reconciliation. A dedicated terminal or full point-of-sale package may be the better choice there, even if it costs more or requires extra equipment. The convenience of Jim is strongest when the operation is light enough that the phone does not become a bottleneck.
Settings and preparation that deserve attention
Before relying on the app in public, I would spend time checking the account and device setup rather than waiting for the first real customer. Make sure you understand where payment details appear, how you recognize a completed transaction, and what you normally do after a customer pays. The most valuable setting is often not a flashy feature but a clear confirmation habit.
I would also review notification behavior. If the phone hides alerts, uses a restrictive battery mode, or is constantly silenced, a seller may miss an important status change. I would not treat a customer’s screenshot or a sound from the phone as final proof by itself. The safer routine is to verify the transaction inside the app before handing over the goods or closing the job.
Screen brightness and phone placement matter more than many people expect. At an outdoor stall, glare can make an amount difficult to read. In a service visit, placing the phone where both people can see it reduces awkwardness and gives the buyer a chance to confirm the total. These are small operational choices, but they make a mobile payment tool feel much more trustworthy.
Jim runs on Android seven or later, so compatibility should be checked before installing it on an older device. That minimum is broad enough for many phones, but an old handset may still create a poor experience through slow performance, weak battery life, or unreliable connectivity. I would use a phone that can remain available for the whole selling period, rather than the oldest spare device in a drawer.
The current version is 1.4.19, and I would keep the app maintained through the normal update process. Updates are especially relevant for finance software because a payment workflow needs to remain stable as phones and operating systems change. I would update before a busy event, not five minutes before opening, so there is time to sign in and test the routine again.
Small habits that make repeat sales faster
Experienced use is less about rushing through individual taps and more about removing decisions. I would keep a short price list beside the phone, group common amounts mentally, and decide in advance where the payment step belongs in the conversation. For a service business, that might be immediately after showing the completed work. For a market seller, it might be after packing the item but before the customer walks away.
Another useful pattern is to create a pre-opening checklist. I would confirm the phone has enough charge, the app opens normally, the network situation is acceptable, and the seller’s records are ready. I would also keep a backup payment option available for situations in which a buyer’s preferred method or the local connection does not cooperate. A mobile reader reduces equipment, but it should not encourage a seller to eliminate every fallback.
For multiple customers, I would avoid leaving the previous transaction visible longer than necessary. After confirming a payment, return to a clean starting point and record the sale while the details are fresh. This reduces the risk of confusing one customer’s amount with the next person’s. It is a modest discipline, yet it becomes valuable during a queue.
A further improvement is to give the customer a consistent explanation. I would say the amount first, show the phone, wait for the confirmation, and then finish the handover. Repeating the same sequence makes the seller look organized and makes it easier to notice when something does not match. This is one of the strongest non-obvious benefits of using a focused app: it encourages a repeatable routine if the seller builds one around it.
Where the convenience has limits
The biggest trade-off is that Jim concentrates the payment experience in one phone. If the phone battery dies, becomes unavailable, or is needed for another urgent task, the selling process can become awkward. A separate terminal has its own inconvenience, but it also keeps payment apart from personal calls, navigation, messages, and other daily phone activity.
Connectivity is another practical consideration. I would not promise myself that every location will feel equally smooth. A seller working in a basement, a crowded venue, or a rural area should test the setup in similar conditions before depending on it. Keeping a backup such as cash acceptance or another established method is sensible, particularly when the sale is important or the customer has already committed time to the visit.
The app may also be less attractive when a business needs sophisticated reporting. If you require staff permissions, product-level inventory, printed receipts, customer accounts, or a detailed refund workflow, a dedicated point-of-sale system will probably provide a more complete structure. Jim’s focused design is a strength for simplicity, but simplicity can feel like a missing layer once the business becomes operationally complex.
I would also separate “paid quickly” from “money managed completely.” Accepting a payment is only one part of running a business. Sellers still need to review their records, understand their own cash flow, and follow whatever financial obligations apply to them. Jim can shorten the collection moment, but it does not remove the need for responsible administration.
Privacy and device security deserve ordinary attention too. I would protect the phone with a screen lock, avoid handing it over unnecessarily, and keep the app on a device that the seller can control. These are not reasons to avoid the product; they are reminders that turning a personal phone into a payment tool changes how carefully that phone should be handled.
How it compares with familiar alternatives
Compared with cash, Jim can be more convenient for customers who do not carry notes and coins, while cash remains useful when connectivity or battery life is uncertain. Compared with a bank transfer, a card-reader workflow may feel more suitable for a quick in-person sale, especially when the seller wants the payment moment to happen directly in front of the buyer. The better choice depends on what the customer already prefers.
Compared with a dedicated card terminal, Jim wins on portability and reduced equipment. A terminal may win on durability, shared use, and the confidence of a business that processes payments continuously. I would choose Jim for mobility and low setup friction, but I would choose dedicated hardware when payment is the central activity of a staffed shop.
Compared with a full point-of-sale app, Jim appears more focused. That is good if the seller wants to collect payments without rebuilding the rest of the business. It is less compelling if the seller expects the payment app to manage stock, employee activity, customer history, and detailed sales analysis in one place. In that situation, integration and depth matter more than having the fewest tools.
My verdict after building a repeatable routine
Jim: sell & get paid instantly is a practical finance app for a specific problem: accepting payments while moving around, without carrying a separate reader. I like it most when the seller prepares beforehand, verifies each transaction inside the app, keeps simple records elsewhere, and maintains a backup for battery or connection trouble.
Its free price makes experimenting less intimidating, and the Everyone rating keeps its presentation broadly accessible. CloudWalk has positioned the app for a straightforward payment experience rather than an elaborate business suite. That focus is exactly why it can feel useful to a freelancer or small seller, but it is also why I would not recommend it as the sole system for a complex retail operation.
The app was released on January 5, 2026, and its current version is 1.4.19. Those details make it worth checking that your phone meets the Android requirement and that the installed version is current before using it for real sales. I would do a complete rehearsal, including the customer-facing explanation and the post-payment record, before taking it to an event or client visit.
My final recommendation is simple: choose Jim if your priority is a portable, phone-centered way to collect card payments and your business can stay organized with a separate record-keeping habit. Skip it in favor of a fuller register or dedicated terminal if you need a multi-person checkout, extensive inventory controls, or a payment setup that remains independent of your personal phone. Used within its natural limits, Jim is most valuable when it turns payment into a calm, repeatable part of the sale rather than another piece of equipment to manage.
Jim: sell & get paid instantly FAQ
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a mobile marketplace designed to help users list items for sale, communicate with potential buyers, and receive payment through the app. It is intended to make local or peer-to-peer selling faster and more convenient by combining product listings, buyer interactions, and payment features in one place. Availability and supported services may depend on your country.
How do I sell an item through the Jim app?
To sell an item, you generally create a listing by adding photos, a title, description, price, and any relevant details about the product’s condition. Clear images and an accurate description can help attract serious buyers. After publishing the listing, you can respond to messages, agree on the transaction details, and follow the app’s instructions for payment and delivery or collection.
Can I really get paid instantly when I sell something?
The app promotes fast payment, but the exact timing may vary depending on the payment method, buyer verification, bank processing times, account status, and local availability. Before completing a sale, review the payment terms shown in the app, including possible fees, withdrawal limits, and processing delays. Never hand over an item solely because a buyer claims to have paid; confirm the transaction inside your account.
Is Jim safe to use for buying and selling?
Jim may provide features intended to support safer transactions, such as in-app communication, account controls, and integrated payment options. However, no marketplace can eliminate every risk. Avoid sharing unnecessary personal information, be cautious of unusually high offers or urgent requests, and keep conversations and payments within the official app whenever possible. For in-person exchanges, choose a public location and follow local safety guidance.
Are there fees or requirements for using Jim?
Fees and account requirements can depend on the type of transaction, payment method, location, and whether you are buying or selling. Some features may require identity verification, a valid phone number, or a supported bank or payment account. Check the current pricing, seller charges, withdrawal conditions, and cancellation rules in the app before listing an item, since these details can change over time.











